
Loan processing fees can reduce the cash you receive without reducing the balance on which repayments are calculated. A quoted loan of 100,000 with a 1,200 fee deducted may put only 98,800 in your account while the scheduled EMI is still based on 100,000.
Use the EMI calculator for the financed principal, rate and term. Keep a separate fee-and-disbursal worksheet so you do not mistake the amount borrowed for the amount available to spend. The examples use fictional currency units and lending terms, not a current loan offer.
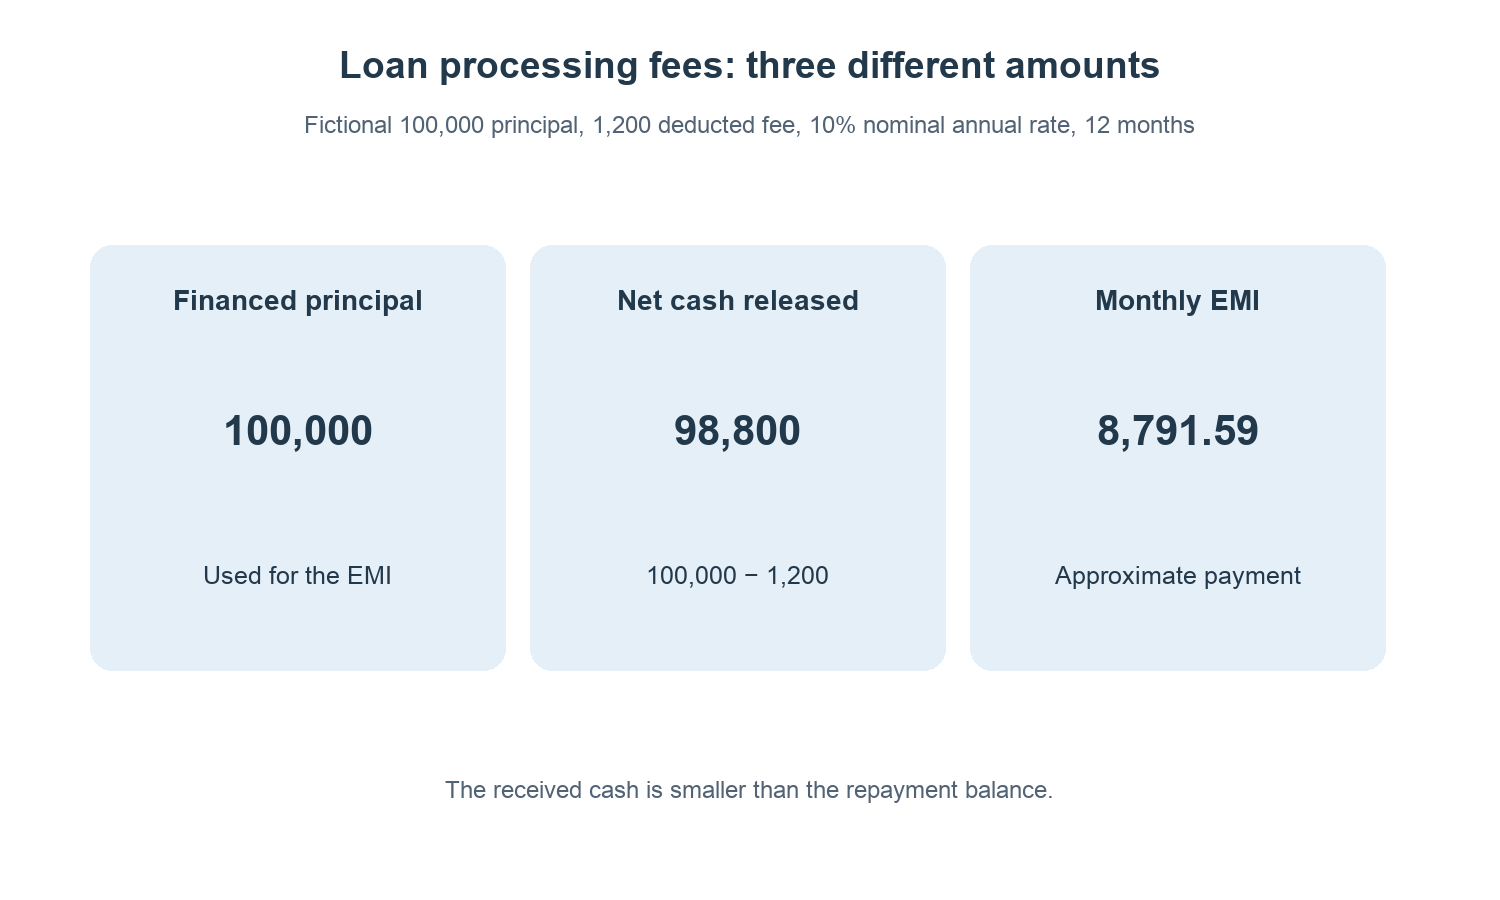
Table of Contents
Loan processing fees affect more than the EMI
Financed principal is the starting balance used in the repayment model. Net disbursal is the cash actually released after deductions. Total cash outflow includes scheduled repayments plus any charges you pay separately.
Loan processing fees may be described as processing, origination or documentation charges. Read the offer’s exact terms rather than assuming the label determines how it is charged. The Consumer Financial Protection Bureau’s installment-loan guidance highlights fees as part of the cost to check in the lender’s disclosures.
This article’s arithmetic assumes a conventional fixed-rate amortizing loan with equal monthly periods, monthly interest equal to the nominal annual rate divided by twelve, and no other charges. Actual contracts may use different accrual dates, taxes, insurance, rounding or repayment structures.
Loan processing fees: a 100,000 loan example
Assume a financed principal of 100,000, a nominal annual interest rate of 10%, twelve monthly payments and a 1,200 fee deducted at release. There are no other charges in the example.
Net disbursal = 100,000 − 1,200 = 98,800
The monthly rate is 0.10 ÷ 12. Using the standard amortizing-payment formula, the theoretical monthly payment is about 8,791.59. Before payment-by-payment cent rounding, the twelve payments total approximately 105,499.06.
| Quantity | Illustrative amount | Meaning |
|---|---|---|
| Financed principal | 100,000.00 | Balance used for the EMI |
| Fee deducted at release | 1,200.00 | Cash not released to the borrower |
| Net cash received | 98,800.00 | Amount available from the disbursal |
| Theoretical total repayments | 105,499.06 | Sum before individual-payment rounding |
| Repayments minus cash received | 6,699.06 | Interest plus deducted fee in this model |
The scheduled interest is about 5,499.06, but the difference between repayments and usable cash is about 6,699.06. Reporting only the interest leaves out the 1,200 fee.
If you enter 98,800 as principal in the EMI calculator, you model a smaller loan than this offer. The fact that the borrower receives less does not by itself reduce the contractual financed balance.
Compare separately paid and financed loan processing fees
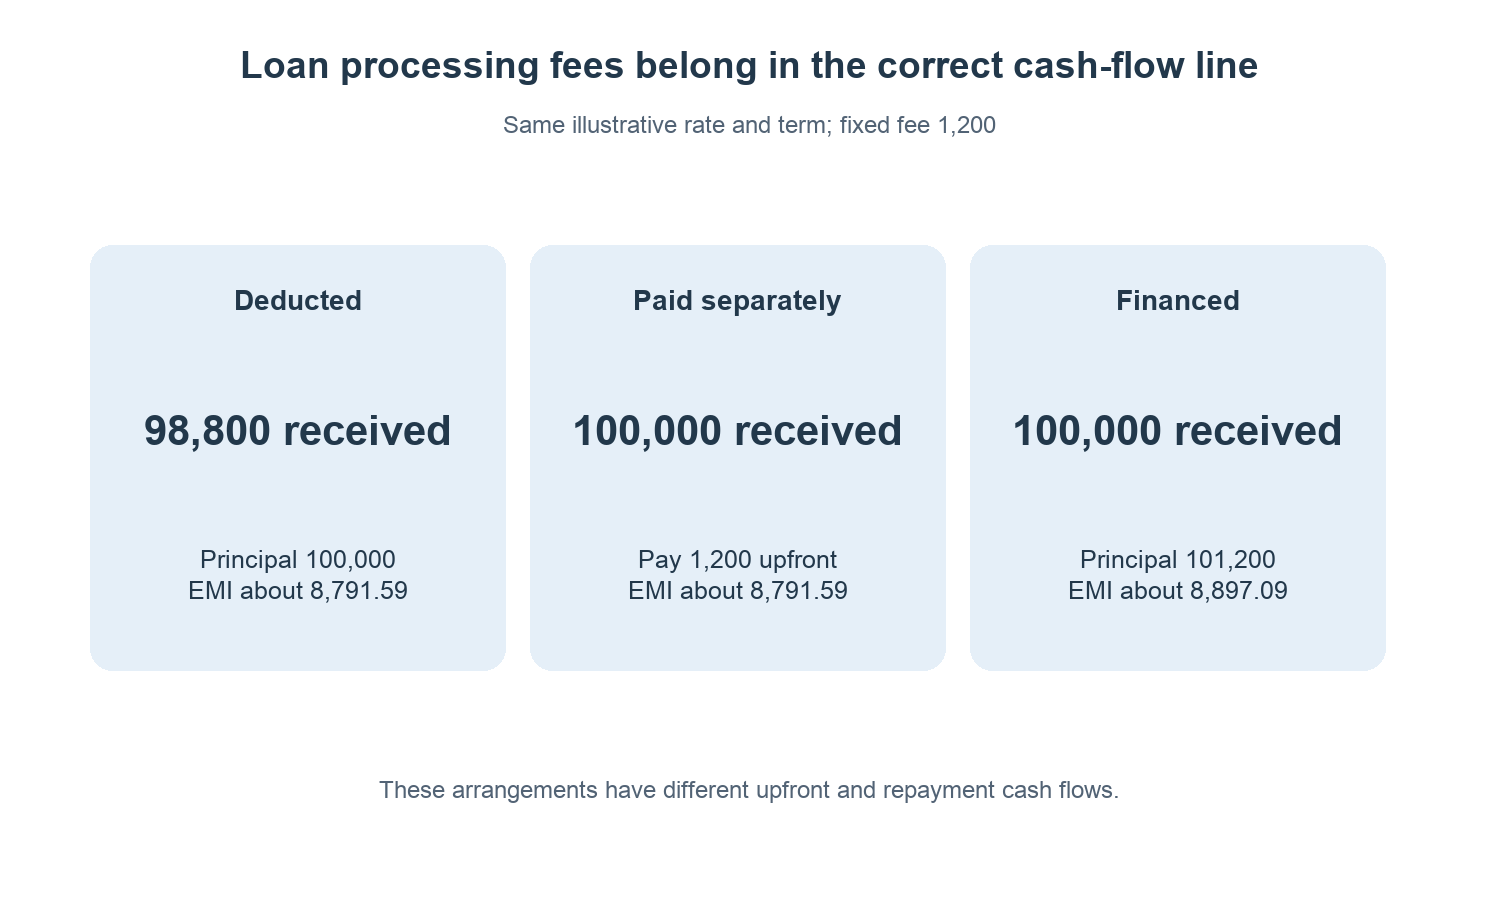
In a separately paid arrangement, the borrower receives 100,000 and pays the 1,200 fee from other funds. The financed principal and EMI can remain 100,000 and approximately 8,791.59. Total outgoing cash is the repayments plus that separate fee.
In a financed-fee arrangement, suppose 1,200 is added to the amount borrowed so the borrower receives 100,000 for their purpose while repaying a principal of 101,200. At the same rate and term, the monthly payment is approximately 8,897.09, and total theoretical repayments are 106,765.05.
| Fee treatment | Financed balance | Cash released | Separate upfront payment | Approximate EMI |
|---|---|---|---|---|
| Deduct 1,200 from release | 100,000 | 98,800 | 0 | 8,791.59 |
| Pay 1,200 separately | 100,000 | 100,000 | 1,200 | 8,791.59 |
| Add 1,200 to financing | 101,200 | 100,000 | 0 | 8,897.09 |
Financing the fee avoids that separate upfront payment in this scenario, but the fee becomes part of the interest-bearing balance. It is not removed from the total cost. Also check whether a percentage-based fee is recalculated on the increased balance; the example assumes a fixed 1,200 charge.
Compare the same cash need and repayment horizon
If you need exactly 100,000 available for a purchase, an offer releasing 98,800 leaves a 1,200 funding gap. Comparing its EMI with an offer that releases the full 100,000 can be misleading unless you account for that gap.
Record the cash needed, net amount released, separate upfront charges, number and timing of payments, any final balloon and required ongoing charges. Then compare those cash flows under the same intended borrowing need.
A smaller EMI can also result from a longer term. It does not automatically mean a cheaper loan. Our loan-term comparison shows why the payment and total-cost questions should be kept separate.
Do not call “total cost divided by cash received” an APR. That ratio ignores when repayments occur and may not follow the jurisdiction’s legally defined APR or effective-rate method. Compare the lender’s required rate disclosures and fee schedule, and ask it to explain any mismatch.
A reproducible calculator check
- Enter 100,000 as the financing amount, 10% annual interest and twelve months for the deducted-fee example.
- Check that the term selector is months, not twelve years.
- Record the approximate EMI and total interest.
- Subtract the 1,200 fee separately from disbursal to obtain 98,800 received.
- For the financed-fee scenario, change only principal to 101,200 and compare the new payment.
The EMI formula guide explains the payment formula. A lender may round each payment and adjust the final installment, so twelve copies of a displayed two-decimal EMI can differ slightly from the full-precision total shown here.
Loan processing fees quoted as a percentage
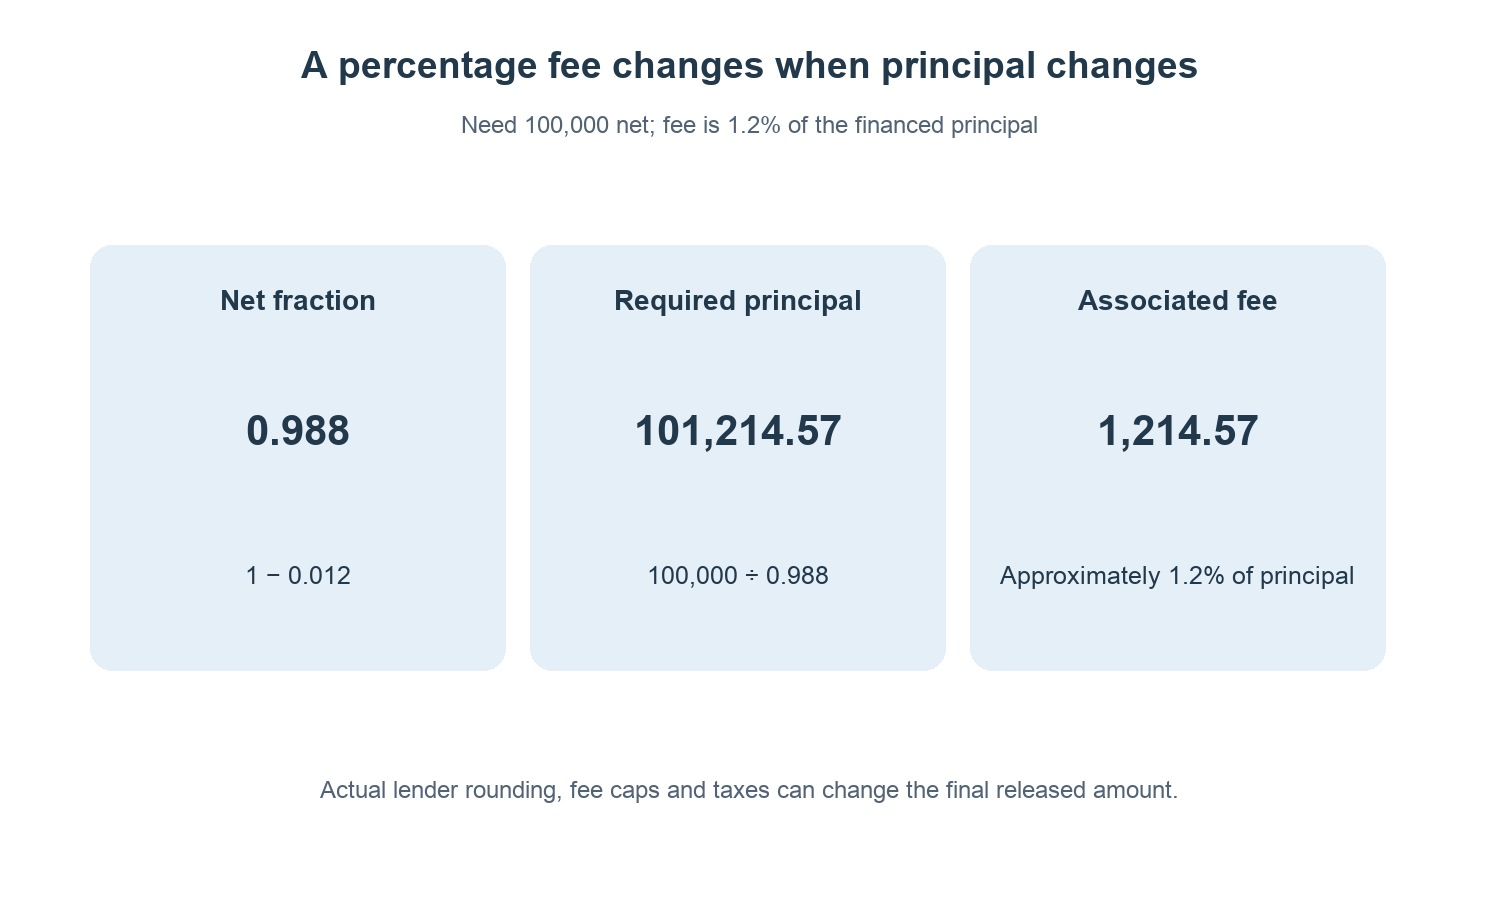
If a fee is 1.2% of the financed principal, a 100,000 principal produces a 1,200 fee. But increasing the principal also increases that fee. You cannot assume the charge remains 1,200 after changing the amount borrowed.
Suppose the fee is deducted from release and you need exactly 100,000 net. Under the stated percentage-only model, net disbursal is principal × (1 − 0.012). Rearranging gives principal = 100,000 ÷ 0.988 ≈ 101,214.57, with an associated fee of approximately 1,214.57.
Simply adding 1,200 to the desired net amount gives a principal of 101,200. Its 1.2% fee is 1,214.40, leaving 99,985.60 net, slightly below the target. The difference is small in this illustration but exposes the circular relationship between a percentage fee and the balance on which it is charged.
| Stated deducted fee | Principal needed for 100,000 net | Fee under the model |
|---|---|---|
| Fixed 1,200 | 101,200 | 1,200 |
| 1.2% of principal | Approximately 101,214.57 | Approximately 1,214.57 |
This is an algebra check, not an instruction to borrow a specific amount. Minimum fees, caps, taxes and the lender’s currency rounding can change the actual required principal. Obtain the final net-release figure from the written offer.
Separate the monthly budget from the upfront budget
Two offers can have the same EMI but require different cash on the start date. In the original separately-paid-fee scenario, the borrower needs the 1,200 fee available outside the scheduled repayments. In the deducted-fee scenario, the immediate issue is the 1,200 shortfall in cash released.
Keep two worksheet lines: “cash needed at or before release” and “scheduled monthly payment.” A monthly affordability comparison that omits the first line can miss a practical funding gap even when its payment formula is correct.
When loan processing fees involve several initial deductions, list them individually rather than combining them into an unexplained difference. For example, a hypothetical 100,000 release with a 1,200 processing fee and a separately identified 300 charge leaves 98,500. Whether either charge is applicable, optional or financed must come from the offer.
Check a payment schedule without manufacturing precision
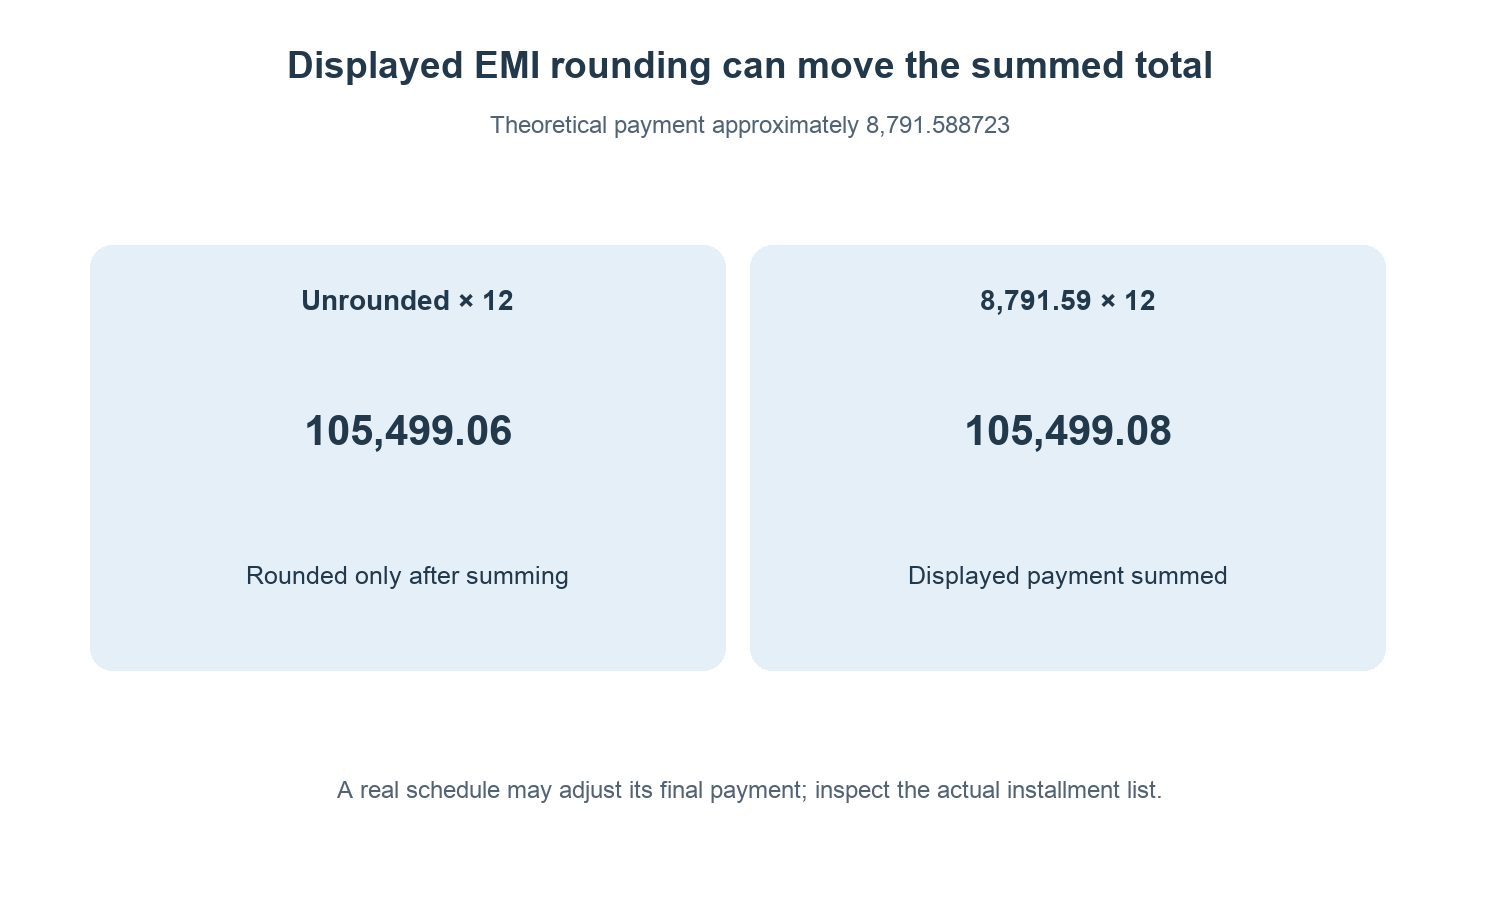
The model’s full-precision payment is approximately 8,791.588723. Displaying 8,791.59 is sensible for a two-decimal currency, but multiplying that rounded display by twelve gives 105,499.08, two cents above the theoretical unrounded total of 105,499.06.
A real schedule may adjust the last installment or apply a specified rounding method. A small rounding difference is not evidence that the fee was hidden; equally, a large unexplained difference should not be dismissed as rounding. Compare the actual installment list and fee lines with the assumptions used in the model.
A comparison record for loan processing fees
Save the offer date, principal, net disbursal, rate type, rate label, payment count, first payment date, fee basis and total disclosed repayments. Include whether a fee is deducted, paid separately or added to the balance. Keep required charges distinct from optional products.
This record lets you change one assumption at a time. If the EMI differs, first check principal, rate and term. If the EMI matches but usable cash differs, inspect the release deductions. If total outgoing cash differs despite matching repayments, inspect separately paid charges.
Common questions
Does a zero-interest offer always have zero borrowing cost?
No. Fees or required charges can create a cost even when the stated interest input is zero. Inspect all cash flows rather than only the interest-rate label.
Should I add the processing fee to principal?
Only if the offer actually finances it. A deducted or separately paid fee belongs in a different part of the worksheet.
Are taxes on a fee included here?
No. Add any applicable taxes or other mandatory charges from the actual offer and identify whether they are deducted, paid separately or financed.
Use the EMI calculator for the repayment balance, then retain the disbursal worksheet beside it.