
Estimate the monthly payment and interest on a fixed-rate, reducing-balance loan. Enter the amount borrowed, annual interest rate and term, choosing years or months. The schedule shows how each payment is divided between principal and interest; fees and lender-specific charges need a separate allowance.
Loan & EMI Calculator
Calculate your monthly installment (EMI) for any loan — home, car, personal, business and more. Enter the asset price and down payment to auto-fill the financing amount, or just enter the loan amount directly.
Tentative Repayment Schedule
How to use the loan and EMI calculator
- Enter the Loan / Financing Amount. Alternatively, enter an asset price and down payment; check the amount filled in before calculating.
- Enter the annual interest rate as a percentage: enter 10.5 for 10.5% per year.
- Enter the loan term and select Years or Months. Ten years and 120 months represent the same term.
- Select Calculate, then review the monthly installment, total interest and total payable. Switch the repayment schedule between monthly rows and yearly totals.
Loan Type identifies your scenario; it does not fetch a lender’s rate or apply product-specific rules. Currency changes the labels, not the interest formula or an exchange rate. Enter every monetary amount in the same currency.
What the monthly payment contains
EMI means equated monthly installment. In this model, each payment covers that month’s interest and pays down part of the original loan, called the principal. Interest is calculated on the remaining balance, so the interest portion usually declines as the loan is repaid. This is the amortization process described by the CFPB.
The estimate assumes a constant rate, equal monthly periods, payments at the end of each period, and no missed payments or additional charges. It does not model daily-interest settlement dates, a changing rate, an interest-only period, a balloon payment, or a flat-rate loan.
The formula and a checked example
M = P × r × (1 + r)n / ((1 + r)n − 1)
- P is the amount borrowed.
- r is the contractual annual interest rate, expressed as a percentage, divided by 100 and then by 12. For 10.5%,
r = 0.105 / 12 = 0.00875. - n is the number of monthly payments. Multiply years by 12.
- M is the monthly principal-and-interest payment. At 0% interest, use
M = P / n.
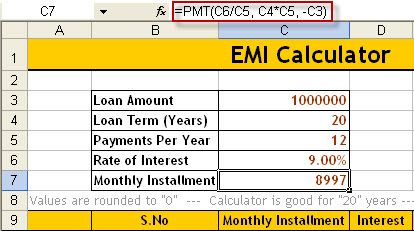
For a loan of 1,000,000 at 10.5% a year over 10 years, using the monthly-period assumptions above:
| Result | Amount |
|---|---|
| Monthly installment | 13,493.50 |
| Total of 120 payments | 1,619,219.96 |
| Total interest | 619,219.96 |
| First month’s interest | 8,750.00 |
| First month’s principal repayment | 4,743.50 |
Totals use the unrounded payment before displaying two decimal places. A lender that rounds every payment may adjust the final installment slightly. This example is arithmetic, not an available loan offer.
Compare offers on the same basis
Hold the loan amount and term constant when comparing rates. Then compare terms separately: extending repayment can reduce the monthly amount while increasing total interest. A smaller payment alone does not establish that an offer is cheaper.
Use the contractual interest rate for the payment calculation. APR also reflects fees, so it is a broader comparison measure and is not interchangeable with the rate input. Compare origination charges, insurance, taxes and early-repayment terms in the actual offer documents.
A flat rate charges interest using the original principal rather than the falling balance. Do not enter a flat quote and interpret this result as its actual repayment schedule. See flat versus reducing-balance interest and the worked EMI formula guide.
Common questions
Can I calculate a zero-interest loan?
Yes. With a 12,000 loan, 0% interest and 12 monthly payments, the model gives 1,000 per month and zero interest. Separate fees can still make a zero-interest offer cost more than its principal.
Can I enter an extra payment here?
This EMI widget has no extra-payment input. For a home-loan scenario, the mortgage calculator includes one. Confirm how your lender applies extra principal and whether it charges a fee.
Will a lender use exactly this schedule?
Not necessarily. Payment dates, interest conventions, fees, rounding and changes to the rate can produce different amounts. Check the lender’s repayment schedule before borrowing. The calculator is an educational estimate, not a credit decision or financial recommendation.